Adaptive Risk Scoring Models Employed by Payment Providers Serving Regulated Betting Markets
Written by Ines Albrecht · Jul 20, 2026
Adaptive Risk Scoring Models Employed by Payment Providers Serving Regulated Betting Markets
Payment providers handling transactions for regulated betting markets rely on adaptive risk scoring models to evaluate each deposit and withdrawal in real time, adjusting scores based on transaction patterns, user behavior, and external signals while maintaining compliance with licensing requirements across multiple jurisdictions.
These models differ from static rule-based systems because they incorporate machine learning techniques that update continuously as new data arrives, allowing providers to respond to emerging fraud tactics without manual intervention each time a pattern shifts.
Core Components Driving Model Adaptability
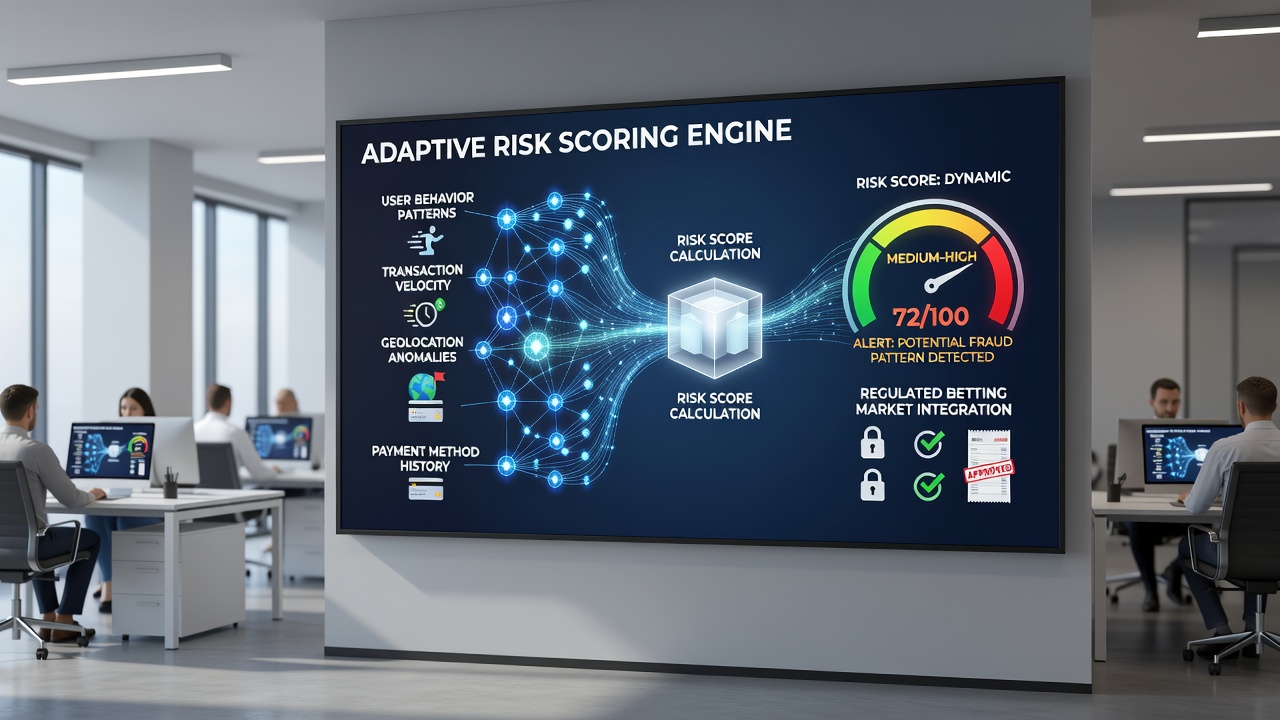
Adaptive systems typically combine several data layers including device fingerprinting, geolocation verification, velocity checks on funding amounts, and historical player profiles, then feed these inputs into algorithms that recalculate risk scores within milliseconds of a transaction request. Researchers at institutions studying financial crime prevention note that the weighting assigned to each factor changes dynamically when market conditions or regulatory alerts indicate heightened threats in specific regions.
Payment processors integrate feedback loops so that approved transactions later flagged for review automatically adjust future scoring parameters, creating a self-correcting mechanism that improves accuracy over successive cycles. Data from the New Jersey Division of Gaming Enforcement shows that platforms employing such adaptive approaches recorded measurable reductions in chargeback ratios during periods of elevated betting activity.
Implementation Across Global Regulated Markets
In Australia, providers serving licensed wagering operators apply these models to align with AUSTRAC reporting obligations, where transaction monitoring must capture both money laundering indicators and responsible gambling triggers without creating friction that delays legitimate player funding. AUSTRAC guidance outlines expectations for real-time screening, and companies have responded by embedding adaptive scoring directly into their gateway infrastructure.
European operators similarly deploy these tools to satisfy varying national standards, with models tuned to flag cross-border transfers that exceed thresholds set by individual member states while permitting rapid processing of routine deposits from verified accounts. The approach allows providers to maintain settlement speeds required by high-volume sports betting platforms during major events.
North American markets present additional complexity because state-level regulations often impose distinct technical requirements on transaction monitoring, prompting providers to maintain multiple model variants that switch based on the licensing jurisdiction tied to each player account.
Integration with Broader Compliance Ecosystems
Adaptive risk scoring rarely operates in isolation, instead connecting to identity verification services, sanctions screening databases, and internal case management systems so that elevated scores trigger automated requests for additional documentation or manual review by compliance teams. Observers note that this layered architecture helps providers demonstrate effective risk mitigation during regulatory audits without creating unnecessary delays for the majority of low-risk transactions.
Updates released in July 2026 by several state gaming authorities emphasized the importance of documenting how models adapt over time, requiring operators to retain audit trails that show parameter changes and the data events that prompted them. Payment providers responded by enhancing logging capabilities within their scoring engines to meet these new documentation standards.
Technical Considerations in High-Volume Environments
Scalability becomes critical when models must process thousands of betting-related transactions per minute during peak periods such as major sporting events or tournament finals, and providers address this by deploying distributed computing resources that allow parallel evaluation of risk factors without compromising response times. Industry reports indicate that optimized implementations achieve sub-second decisioning even when incorporating dozens of input variables.
Model training draws on anonymized datasets aggregated across multiple operators, enabling the identification of subtle patterns that individual providers might miss when analyzing only their own transaction streams. Academic studies examining payment flows in gaming ecosystems have highlighted how collaborative data approaches strengthen detection of coordinated fraud attempts that span several platforms.
Conclusion
Adaptive risk scoring models continue to evolve alongside regulatory expectations and technological capabilities, providing payment providers serving regulated betting markets with tools that balance transaction speed against the need for robust fraud prevention and compliance. As licensing frameworks expand into additional jurisdictions, the ability of these systems to recalibrate quickly supports both operational efficiency and adherence to evolving standards.